

june 1815, all of london is waiting on waterloo.
napoleon against wellington. the battle that will decide the fate of europe. and the outcome will decide the price of every bond in the market.
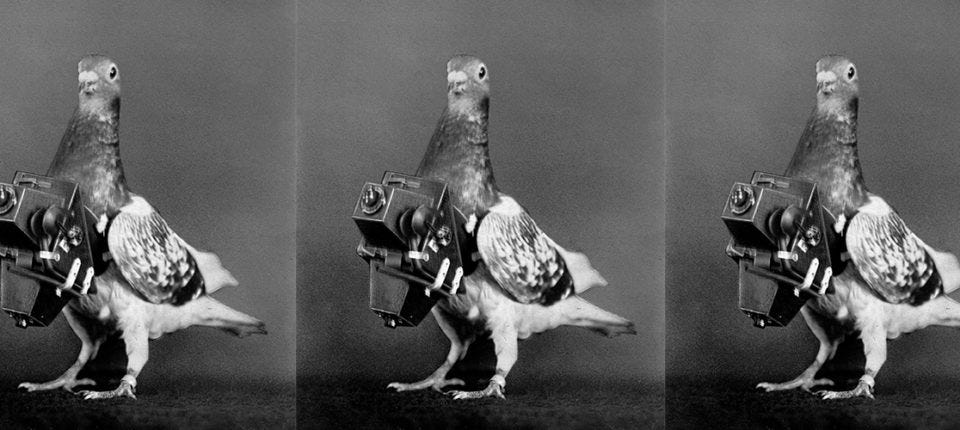
but one family has spent years preparing for this moment. the rothschilds have built the fastest private courier network in europe. riders, boats, and, so the legend goes, carrier pigeons.
napoleon lost.
nathan rothschild knew a full day before the government did. and he traded on it. the legend prices his gain in the hundreds of millions in today’s money.
the edge was never capital. it was seeing first. the couriers were not a messaging business. they were sensors, pointed at a continent, owned by the one family that understood what a day’s head start was worth.
this document is about the courier networks being built right now. and about the people building them, who mostly aren’t saying so.
intelligence is only worth what it can see.
i tracked the last fifteen acquisitions across the most sophisticated serial acquirers of vertical software. Constellation Software, OpenAI, Beacon. deal after deal, the same shape: buy the layer that serves a market, and you see that market move before anyone else does.every shift in the economy shows up in the books of the people who serve it, months before it shows up anywhere else.
they are buying the pigeons.
the moat is moving. software is commoditizing, and value migrates up a layer each era. SaaS is over. service-as-software runs the tool and sells the outcome. but extrapolate the trendline to where it terminates: models become a utility, operations become a commodity, and distribution, the network that gives intelligence its eyes, becomes the last layer standing.
i call that phase the “prediction economy”: the point at which the winners in vertical markets are no longer the ones who automate the work, but the ones who see the market through the work. and the advantage compounds: seeing first becomes a selection advantage, then a pricing advantage, then a timing advantage, until it converts into a compounding position, and finally into a terminal asset. you become the reference layer the market prices itself against.
the player becomes the house.
and the position, once built, cannot be rebuilt. because the advantage is not capital, talent, or software. it is accumulated history. a market panel that started recording in 2026 can never be caught by one that starts in 2028. history is the one thing money can’t compress.
the rothschild edge, industrialized.
from software to infrastructure
three things changed in the last eighteen months. AI collapsed the rebuild cost. the buyers moved up the stack. and capital piled up faster than credible vehicles to absorb it.
level one: sell the tool. classical SaaS. 2 to 5% of value captured. in june 2025, Wix paid $80 million for Base44, an app-building platform six months old, built by one man, with no outside funding. one person, half a year, eighty million. a competitor with a coding agent replicates most SaaS in weeks. code depreciates.
level two: sell the outcome. same software, but you run it yourself. Crosby sells legal filings. Corgi underwrites insurance policies, full-stack, $2.6B valuation eighteen months after founding. capture jumps to 30-60%.
Sam Lessin takes it further: buy the businesses you operate better. Metropolis raised $1.8 billion and took SP+ private. four thousand parking locations, four billion a year in payments, one company’s computer vision. the AI rollup wave is this argument in execution. Crescendo, Long Lake, Dwelly, Titan. all doing the same thing in different verticals.
level two works. but ownership is a capture structure, not a level. a level monetizes a different object entirely. and the defensibility question doesn’t go away: every Metropolis has a competitor two years behind it with the same thesis and a cheaper cost of capital. Long Lake and Dwelly are the proof. same band. two geographies. funded independently.
run the sequence forward. level one goes to free. HubSpot proved that a decade ago. level two goes to commodity. every credible operator will have the automation.
software stops being a product and becomes infrastructure. everyone has it. nobody wins on it.
reach, then sight.
april 2026. OpenAI makes its first media acquisition: TBPN, a daily tech talk show. fifty-eight thousand youtube subscribers. reported at hundreds of millions. run the math per subscriber and the deal is absurd. run it per room reached and it’s cheap. the company whose models everyone rents concluded the scarce asset wasn’t the model. it was the channel.
HubSpot is running the same play as a series. The Hustle in 2021. Starter Story in february 2026.
that’s reach. rooms entered.
the serial acquirers went a level higher.
Constellation bought Keypoint Intelligence in may 2026. not a tool that operates in the digital-imaging vertical: the benchmark authority the vertical measures itself against.
Beacon paid eight figures for RealEstateAPI in march: bootstrapped, property data on 150 million american homes, three hundred customers. not a tool that operates in a market. the data layer under one. and Beacon’s pitch to founders says it plainly: as AI turns competence into a commodity, the scarce asset left is trust. trust is distribution by its human name. what took Constellation three decades, venture capital is trying to manufacture inside a single fund cycle.
the buyer of the software is advertising the data.
that’s sight. not rooms entered. rooms understood.
and the tape is longer than the AI cycle. Monsanto paid a billion for Climate Corp in 2013. Moody’s paid two billion for RMS in 2021. and Verisk, an insurer data consortium that grew into a listed company, is the terminal form: the panel outlived every tool around it.
two decades of tools. five years of reach. now sight, with deals landing months apart. the intervals shorten. the shelf doesn’t restock. most verticals never built a Keypoint. behind most of the economy there is nothing to acquire.
the tape terminates in a shortage.
what remains scarce?
General Catalyst committed $1.5 billion of a single fund to AI rollups. Thrive is raising a permanent vehicle north of a billion. Beacon has raised over half a billion across three rounds. Metropolis took another $1.6 billion in november 2025. J.P. Morgan arranging a billion-dollar term loan for a parking startup.
Peter Thiel wrote in 2014: “superior distribution alone can create a monopoly, even without a better product. a better product alone cannot.”
the capital knows. the buyers know. the question is what they’re buying toward.
the tools are free. the operations are commodity. ownership terminates at the value of the work being done.
what remains scarce is what the buyers on this page are already moving toward. not the software. not the operation. the informational advantage the distribution creates. who is churning, who is growing, whose margins are compressing, where the breaches are landing.
the smartest operators will stop monetizing the user entirely, because friction slows distribution, and distribution is the sensor grid. the user isn’t the customer. the user is the instrument.
that is the third level. part 2/4 names it precisely.
the full thesis is at predictioneconomy.ai
part 2/4: tthe mechanism that generates economy-scale signal, and the one kind of firm everyone has been mispricing